 HART PROPERTY
D'Leedon
A practical review of D'Leedon for real buyers.
- District: 10
- Region: CCR
- Type: 99-year Leasehold (Condo + Cluster Houses)
- Nearest MRT: Farrer Road (CC20), ~700m
- Architect: Zaha Hadid Architects
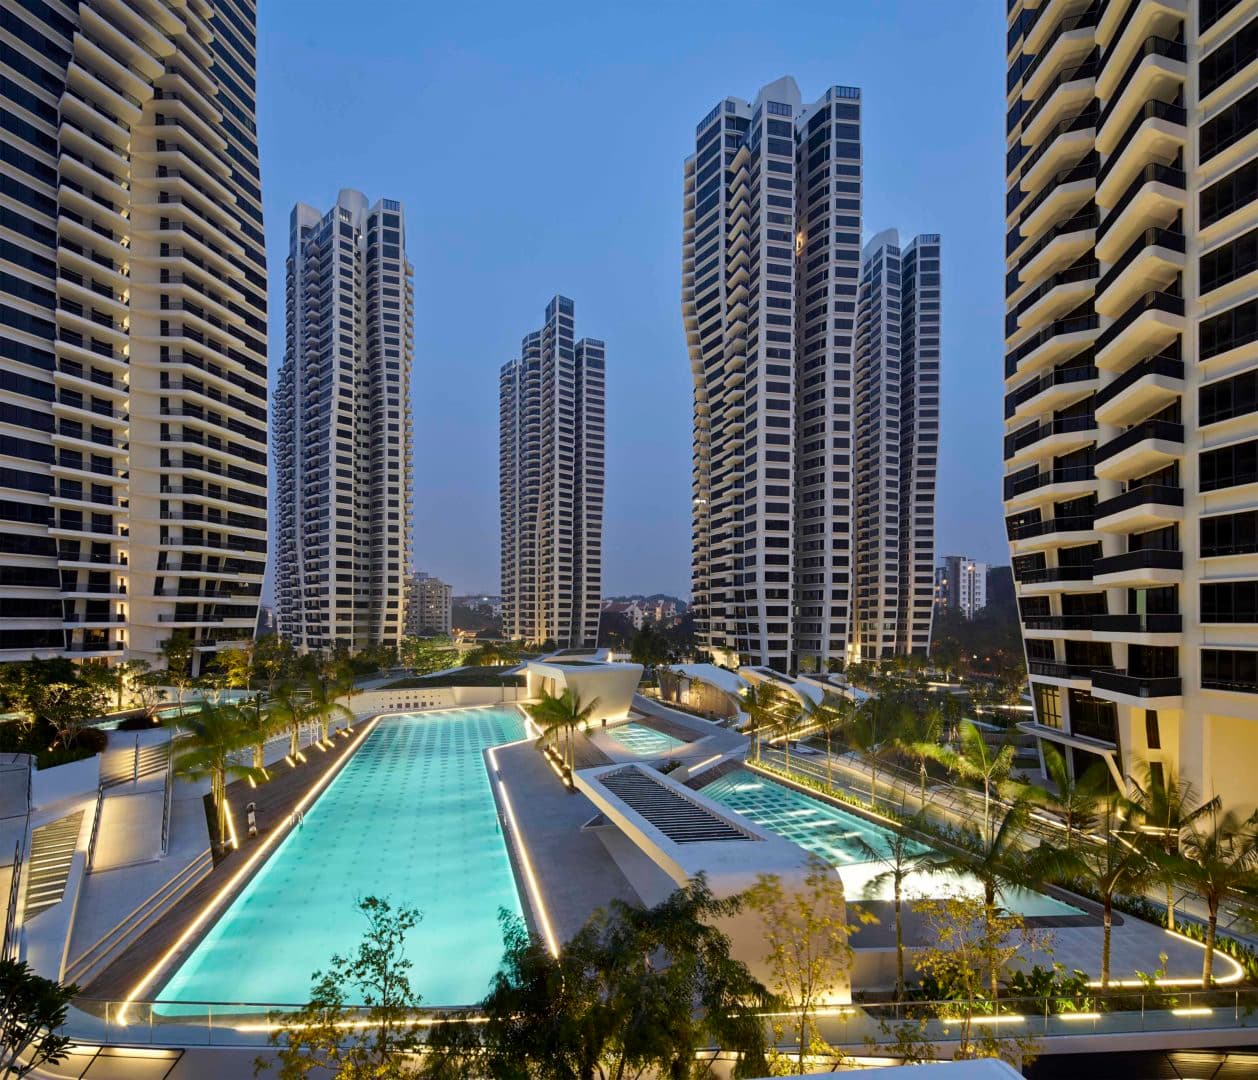
The repricing has already happened. The launch of Skye at Holland and One Holland Village Residences, both 99-year leaseholds in the same district, re-rated D10 leasehold expectations over 2025 and into 2026. D'Leedon has moved with it. You are not early to this trade anymore.
Buyers here are here for the lifestyle, not a pure investment play. Foreigners make up ~15% of owners, which historically supports pricing. But with ABSD now at 60% for foreigners, that buyer pool has materially shrunk. Your exit paths are narrower than they were five years ago.
Lease decay is the key headwind. At 83 years remaining, buyers with a long horizon need to price in tenure erosion. Act before the lease crosses into the 7X-year range or a GLS Holland Plain launch gives you a second window.
Details
Launch prices for each type
D'Leedon launched in late 2010 at an average of ~$1,680 psf, with early buyers entering at $1,500–$1,800 psf. The Zaha Hadid premium drew strong initial demand. 82% of the first 250 released units sold within the first month.
| Type | Typical size range | Launch PSF (approx) | Est. launch quantum (approx) |
|---|---|---|---|
| 1BR+Study | ≈ 700–850 sqft | ~$1,600–$1,750 psf | ≈ $1.1m–$1.5m |
| 2BR | ≈ 850–1,000 sqft | ~$1,600–$1,750 psf | ≈ $1.4m–$1.8m |
| 2BR+Study | ≈ 1,000–1,200 sqft | ~$1,600–$1,750 psf | ≈ $1.6m–$2.1m |
| 3BR | ≈ 1,200–1,600 sqft | ~$1,600–$1,750 psf | ≈ $1.9m–$2.8m |
| 3BR+Study | ≈ 1,500–1,900 sqft | ~$1,650–$1,800 psf | ≈ $2.5m–$3.4m |
| 4BR | ≈ 1,900–2,400 sqft | ~$1,650–$1,800 psf | ≈ $3.1m–$4.3m |
| Garden House | ≈ 3,000–4,000 sqft | ~$1,700–$1,900 psf | ≈ $5.1m–$7.6m |
| Penthouse | ≈ 4,000–6,000+ sqft | ~$1,800–$2,000 psf | ≈ $7.2m–$12m+ |
Price trend
Median $PSF by year based on resale transactions. Years with fewer than 3 transactions are shown as estimates.
Recent resale transactions (2024–2025): median ~$1,976 psf (1BR), ~$1,993 psf (2BR), ~$2,017 psf (3BR), ~$1,960 psf (4BR). 4BR median is nudged down by a small number of very large cluster/penthouse units. The 2015–2017 trough at ~$1,400–$1,500 psf represented the CCR soft period. Buyers who entered then are sitting on the strongest gains.
Nationality by residential status
Breakdown (as provided):
Foreigner ownership at ~14.81% is relatively high and reflects D'Leedon's prestige CCR positioning. However, with ABSD now at 60% for foreigners, this buyer pool has been severely constrained. That 15% figure reflects historical buying, not current demand. Do not assume foreign buyers are a reliable exit path.
Comparison with nearby properties (sale & rent)
| Condo | TOP | Tenure | Median sale psf (2025Q4–2026Q1) | Median rent psf/mo (2025Q4–2026Q1) | Distance |
|---|---|---|---|---|---|
| D'Leedon | 2014 | 99y | ~$2,045 psf | ~$5.43 | 0m |
| Villa Delle Rose | 1994 | Freehold | n/a | ~$3.20 | ~500m |
| Sommerville Park | 1993 | Freehold | ~$2,188 psf | ~$4.05 | ~600m |
| Sommerville Grandeur | 2001 | Freehold | ~$2,190 psf | ~$3.89 | ~700m |
| Gallop Gables | 1996 | Freehold | ~$2,421 psf | ~$4.39 | ~400m |
| Gallop Green | 2002 | Freehold | ~$2,673 psf | ~$4.94 | ~450m |
| Leedon Residence | 2015 | Freehold | ~$2,810 psf | ~$6.41 | ~300m |
| Leedon Green | 2023 | Freehold | ~$2,878 psf | ~$6.37 | ~350m |
| One Holland Village Residences | 2029 | 99y | ~$3,132 psf | ~$8.44 | ~1,200m |
| Hyll On Holland | 2024 | Freehold | ~$2,843 psf | ~$6.88 | ~800m |
| Skye At Holland | 2029 | 99y | ~$2,950 psf | n/a (TOP 2029) | ~1,000m |
| Upperhouse At Orchard Boulevard | 2029 | 99y | ~$3,421 psf | n/a (TOP 2029) | ~2,000m |
Note: Median sale psf and median rent psf computed from actual transactions Oct 2025 – Mar 2026 in our database. Villa Delle Rose has no sale transactions in this window. Gallop Gables, Gallop Green, and Sommerville Grandeur each have 1 sale transaction in this window. Skye At Holland sale data covers its full launch period (Oct 2025 onwards). Skye At Holland and Upperhouse At Orchard Boulevard have no rental data (TOP 2029, not yet completed).
Source: URA transaction data. Each point is the average PSF of all transactions in that quarter.
Source: URA rental contract data. Each point is the average rental PSF of all contracts in that quarter.
Source: INLIS. 4BR median is suppressed in 2014 due to insufficient data. 4BR is pulled down by large cluster/penthouse units in earlier years. 2026 is partial year (Jan–Feb only); 2BR 2026 is based on 1 transaction.
Leasehold condos in this area consistently show lower profitability than their freehold neighbours. This is typical for CCR: the buyer pool is narrower. HDB upgraders and families moving out of public housing gravitate toward RCR, not CCR. CCR demand is driven by wealth preservation, lifestyle, and foreign/PR buyers, all of which have been constrained by ABSD increases. Freehold properties in the same pocket have more exit paths and therefore command higher resale premiums over time.
Analysis and Exit strategy
Pricing
D'Leedon launched at ~$1,680 psf in 2010–2011. For the first several years post-TOP in 2014, prices stagnated in the $1,300–$1,600 psf range as the broader CCR market was sluggish. The real story began post-2020.
Recent resale transactions (2024–2025) are trading at ~$1,960–$2,060 psf depending on unit type (medians from 2024–2025 transactions). For buyers who entered early in the $1,300–$1,500 psf range during the soft years, this represents strong capital appreciation.
The key pricing tension is the leasehold discount vs freehold neighbours. Leedon Green (freehold, 2023) median ~$2,923 psf. Gallop Green (freehold, 2002) median ~$2,647 psf. Leedon Residence (freehold, 2015) median ~$2,759 psf. D'Leedon at ~$1,976 psf median carries a significant leasehold discount, roughly 30–50% below neighbouring freeholds, but the Zaha Hadid brand, mega-development liquidity, and school proximity anchor its demand floor.
On a quantum basis, D'Leedon is one of the more accessible CCR entry points for families who want the D10 address and school proximity without paying Leedon Green or Leedon Residence premiums. A 3BR at ~$1,976 psf on 1,300 sqft works out to ~$2.57m, versus Leedon Green at ~$2,923 psf coming to ~$3.8m for similar size. That is a ~$1.2m quantum difference for the same bedroom count in the same neighbourhood.
A structural tailwind worth noting: the CCR–RCR price gap has been narrowing steadily and hit its narrowest point in 2025 (PropNex Research / URA Realis data). In 2025 the CCR–RCR gap was just ~10%, down from 60–80% gaps seen in the mid-2000s. This means CCR is becoming more accessible relative to RCR. Buyers who previously ruled out CCR on affordability grounds are now reconsidering, which structurally supports demand for lower-psf CCR entry points like D'Leedon.
On the supply side, the Holland Plain GLS site, the closest new government land sale to D'Leedon, will act as a price anchor for the area. New launches on GLS sites in this pocket typically price at a premium to existing resale stock, which re-anchors what buyers consider reasonable for the neighbourhood. If Holland Plain launches at $3,000+ psf (a credible expectation given recent CCR land costs), D'Leedon at ~$1,976 psf will look increasingly compelling on a relative basis and could compress the discount to neighbouring new supply.
Even within the D10 leasehold segment, it's worth stress-testing the raw psf gap honestly. Skye at Holland (99-year, TOP 2029) transacts at ~$2,950 psf, One Holland Village Residences (99-year, TOP 2029) at ~$3,160 psf, and Upperhouse at Orchard Boulevard (99-year, TOP 2029) launched at ~$3,312 psf. At face value that looks like D'Leedon has large room to grow, but the age-adjusted picture is different. Applying a rough ~$50 psf per year of vintage discount, a 2029 leasehold at $2,950 psf implies a 2014-vintage equivalent of ~$2,950 minus ($50 x 15) = ~$2,200 psf. That is precisely where D'Leedon has already repriced to in late 2025 and early 2026. The Holland Village new leasehold launches have largely had their re-rating effect already. Honest assessment: beyond what has already happened, the path to meaningfully higher psf requires a GLS Holland Plain launch to force another re-rating. Without that catalyst, D'Leedon sits roughly at fair value for its age and tenure within the D10 leasehold stack.
Lifestyle & Facilities
At 1,715 units across 840,000 sqft, with 78% of land given to gardens and facilities, D'Leedon punches well above its weight on amenity depth. Multiple pools, tennis courts, basketball courts, gym, jogging tracks, and spa pavilions cater to a wide range of lifestyles. The scale also means better managed common costs spread across a large community.
Proximity to Singapore Botanic Gardens (UNESCO World Heritage Site), Dempsey Hill, Holland Village, and Orchard Road gives residents a rich lifestyle catchment. Farrer Road MRT (CC Line) is ~700m walk, functional but not premium MRT proximity. The 1km Nanyang Primary zone is the single biggest draw for family buyers.
The curved Zaha Hadid architecture comes with a real trade-off: layouts are comparatively inefficient. Non-rectangular rooms, curved walls, and awkward corners reduce usable space relative to the stated sqft. A 1,216 sqft unit at D'Leedon will feel smaller in practice than a 1,216 sqft unit in a conventional development. This narrows the target buyer — practical family buyers and HDB upgraders tend to prioritise liveable rectangular layouts, while D'Leedon appeals more to lifestyle buyers, investors, and those drawn to the architecture. It is part of why the exit pool here skews narrower than a typical RCR or even CCR development.
Lease Decay Consideration
At ~83 years remaining, D'Leedon is entering the phase where lease decay becomes a visible factor in bank valuations and buyer sentiment. Typically, leasehold properties face steeper psf headwinds below 80 years. Buyers on a 10+ year horizon should model lease decay into their exit assumptions, particularly if selling to owner-occupiers (as opposed to investors or foreigners less concerned by tenure).
On en-bloc: historically, successful collective sales in Singapore have almost always involved properties with remaining leases well below 60 years, where the land value unlocked by redevelopment is large enough to compensate owners meaningfully above market. At 83 years remaining, D'Leedon is nowhere near that territory. Any realistic en-bloc scenario is at minimum 20+ years away, and would require 1,715 units to reach 80% consensus, which is one of the hardest thresholds in Singapore property history. Do not factor this into your exit thinking.
7 Decision Points
Disclaimer: This is my assessment and is based on each individual's needs.
Time Horizon
5–7 years
Lease decay pressure accelerates meaningfully below 80 years, so a 5–7 year horizon keeps the exit in the 76–78 year range. Still liquid, but the window for premium pricing is tightening. Shorter horizons (3–4 years) are fine for investors with a clear rental-then-sell strategy, given strong D10 rental demand.
Exit Paths
For Current Owners
The 2025–2026 repricing driven by the Holland Village new leasehold launches has likely already played out. D'Leedon is now sitting at approximately its age-adjusted fair value (~$2,200 psf) within the D10 leasehold stack. Outside of a GLS Holland Plain launch forcing another re-rating, there is no clear catalyst for significant further appreciation. You should not expect annualised returns to improve meaningfully from here if you hold.
The honest picture on timing: now feels like the right moment to exit. The re-rating has happened and prices are at a high. If you choose to wait:
- Watch the Holland Plain GLS tender result first. If it prints above $3,000 psf, that is your next exit window.
- Exit before the remaining lease crosses into the 7X-year range. Once you're below ~78 years, buyer psychology shifts and pricing leverage weakens.
Waiting 5–8 years is unlikely to produce significant downside, but it is equally unlikely to produce meaningfully better annualised returns. You are already in the lower bracket compared to the freehold neighbours in this area. The opportunity cost of staying is real.
The case for exiting now is stronger than the case for waiting. Depending on your budget and risk appetite, there are alternatives in this market with higher annualised return potential. Get in touch for a personalised comparison of what your exit proceeds could do.